For sponsors and portfolio company leaders, this presents a constant challenge. Shifting market conditions, intense buyer scrutiny, and unpredictable exit timelines can quickly expose weaknesses. Suddenly, gaps in financial reporting, a shallow management bench, customer concentration, or a poorly executed value creation plan become glaring liabilities that can erode value and derail a transaction.
This article provides a practical framework for navigating the path to a successful exit. We’ll cover how to assess readiness, build a measurable value creation plan, prepare for the rigors of diligence, select the right exit route, and coordinate the final transaction process for maximum value.
Key Takeaways
- Exit readiness is an ongoing value-creation discipline, not a last-minute cleanup exercise before a sale.
- Buyers demand hard evidence of sustainable performance, transferable operations, a capable management team, and a credible plan for future growth.
- A strong readiness program connects every operational initiative to measurable financial outcomes and maintains an organized record of that progress.
- Early valuation, diligence preparation, and advisor coordination give sponsors greater control over timing, terms, and the narrative.
What Does Exit Readiness Mean in Private Equity?
In a private equity context, exit readiness is the state where a portfolio company can withstand intense buyer scrutiny, prove its realized value creation, and present a credible, substantiated plan for continued growth after the transaction. A profitable company is not automatically a sellable asset.
Many profitable companies are not transaction-ready. Healthy cash flow can still sit beside weak monthly reporting, an indefensible normalized-earnings bridge, thin process documentation, or a team that cannot operate without constant sponsor intervention.
Would the business run smoothly if the key leader took a 30-day vacation? If not, it is not ready.
Readiness unfolds across four connected dimensions:
- Financial readiness: Accurate, timely reporting; defensible EBITDA with clear add-backs; reliable forecasts; working-capital visibility; and a grounded valuation range
- Operational readiness: Scalable processes, modern systems, documented controls, and low dependence on any single owner or executive so the company can run and grow under new ownership
- Commercial readiness: Customer and supplier diversification, meaningful recurring or contracted revenue, clear differentiation, and a data-backed growth story—for example, no single customer above about 10–15% of revenue
- Leadership and governance readiness: Experienced leaders in key seats, clear decision rights, succession plans for critical roles, and sponsor–management alignment on exit narrative and timing
While the ideal preparation period depends on the company and its market, readiness should begin at acquisition or shortly after a value creation plan is set. Treat it as a continuous build, not a last-minute sprint.
Build a Measurable Value Creation Plan Before the Sale Process
A theoretical improvement plan won’t impress a sophisticated buyer. They want value creation already showing up in the company’s results. A PE-ready plan links every initiative to an owner, a timeline, an operational KPI, and a tangible financial impact—with evidence to back it up.
Buyers will dig into the core value levers to validate your story.
Revenue Quality and Growth
Buyers look past a rising top line. They scrutinize:
- Recurring revenue: Subscription or multi-year contracts lower perceived risk and often support higher multiples
- Pricing power: Ability to raise prices without churn signals a durable market position
- Customer metrics: Retention, acquisition cost, and lifetime value under real diligence review
- Diversification: Less concentration in a few accounts; broader markets or channels
Profitability and Cash Generation
Buyers treat sustainable profitability as table stakes. Focus on:
- EBITDA improvement: Margin gains tied to procurement, automation, or cutting unprofitable lines
- Working capital: Tight control of inventory, receivables, and payables to free cash
- Cost structure: A scalable base free of one-time or owner-only expenses that won’t transfer
Scalability and Transferability
The business must transfer as a clean asset. That requires:
- Documented processes: SOPs for every critical function
- Systems and technology: Modern CRM, ERP, and financial systems as a single source of truth
- Management depth: Cross-trained teams so the company does not depend on the founder or a few executives
A McKinsey analysis found that assets sold in 2024-25 had median revenue growth 2–3 percentage points higher than assets that stayed in a PE portfolio. That does not prove causation, but it shows buyers favor companies with a documented record of outperformance.
Track these improvements carefully. You give diligence a clear story of what you already delivered—and the credible upside left for the next owner.

Prepare the Portfolio Company for Financial and Commercial Due Diligence
Clean, consistent, and decision-useful financial reporting is the foundation of a smooth exit process. If a buyer can’t trust your numbers, the deal is at risk. Preparation means having detailed monthly reporting, budget-versus-actual analysis, clear cash-flow visibility, and operational metrics that reconcile with the financials.
A pre-sale quality of earnings (QoE) review is one of the most valuable exercises a company can undertake. It acts as a dress rehearsal for buyer diligence, forcing you to assemble the key documents and defend your numbers.
Key information for a sell-side QoE typically includes:
- Historical financial statements and tax returns
- Detailed revenue breakdowns (by customer, product, geography)
- A full list of proposed EBITDA adjustments and add-backs
- Analysis of working capital, debt-like items, and capital expenditures
- The assumptions driving your financial forecast
This process uncovers issues before buyers do. According to Deloitte, any pro forma EBITDA adjustments—such as annualizing the benefit of a recent cost reduction—require a clear narrative and substantiation to gain buyer confidence. An unsupported add-back is a red flag. A sell-side QoE helps you pressure-test these adjustments and prepare management to answer tough questions.
Beyond financials, prepare for commercial, legal, and operational diligence. Buyers will test the story behind the numbers, so gather evidence for:
- Market size assumptions and competitive positioning
- Customer retention and concentration claims
- Material contracts, intellectual property, and employment matters
- Potential compliance gaps that could slow closing
Engage qualified legal and tax advisors early so these areas are reviewed before diligence starts.
Start building your data room early, not after the first buyer request:
- Organize all source documents under a clear index
- Assign an owner for each file
- Establish version control before sharing begins
A well-organized data room signals professionalism and transparency, shortening the typical 30-to-90-day diligence period and building buyer confidence from day one.

Select the Exit Route and Position the Investment for the Right Buyer
You don’t need to commit to a single exit route prematurely. A well-prepared company can attract multiple buyer types, creating competitive tension that drives better terms.
The principal PE exit routes include:
- Strategic Sale: A sale to a corporate buyer in the same or an adjacent industry, often driven by synergies.
- Sponsor-to-Sponsor Sale: A sale to another private equity firm, which sees an opportunity for a "second bite of the apple."
- Recapitalization or Continuation Vehicle: A transaction that provides liquidity to existing investors while the sponsor retains control, often rolling the asset into a new fund.
- Management or Family Succession: A transfer of ownership to the existing management team or next generation, which requires careful financing and planning.
- Initial Public Offering (IPO): A viable route only for companies with significant scale, mature governance, and a profile that will appeal to public market investors.
The likely buyer profile should shape your preparation:
- Strategic buyers focus on cost synergies, customer overlap, and integration fit
- Financial sponsors test the platform’s capacity for add-on acquisitions and leverage
Once preparation matches the buyer you want, timing becomes the next lever. It depends on external market conditions and internal readiness. Exits often line up with a completed operational initiative, key contract renewals, or the point when management shows full command of the business and its growth plan.
Market conditions move on their own track. Segments can diverge—for instance, global strategic exit value may rise in a given year while US middle-market deals with corporate buyers decline.
Create a Practical 12- to 36-Month Exit-Readiness Roadmap
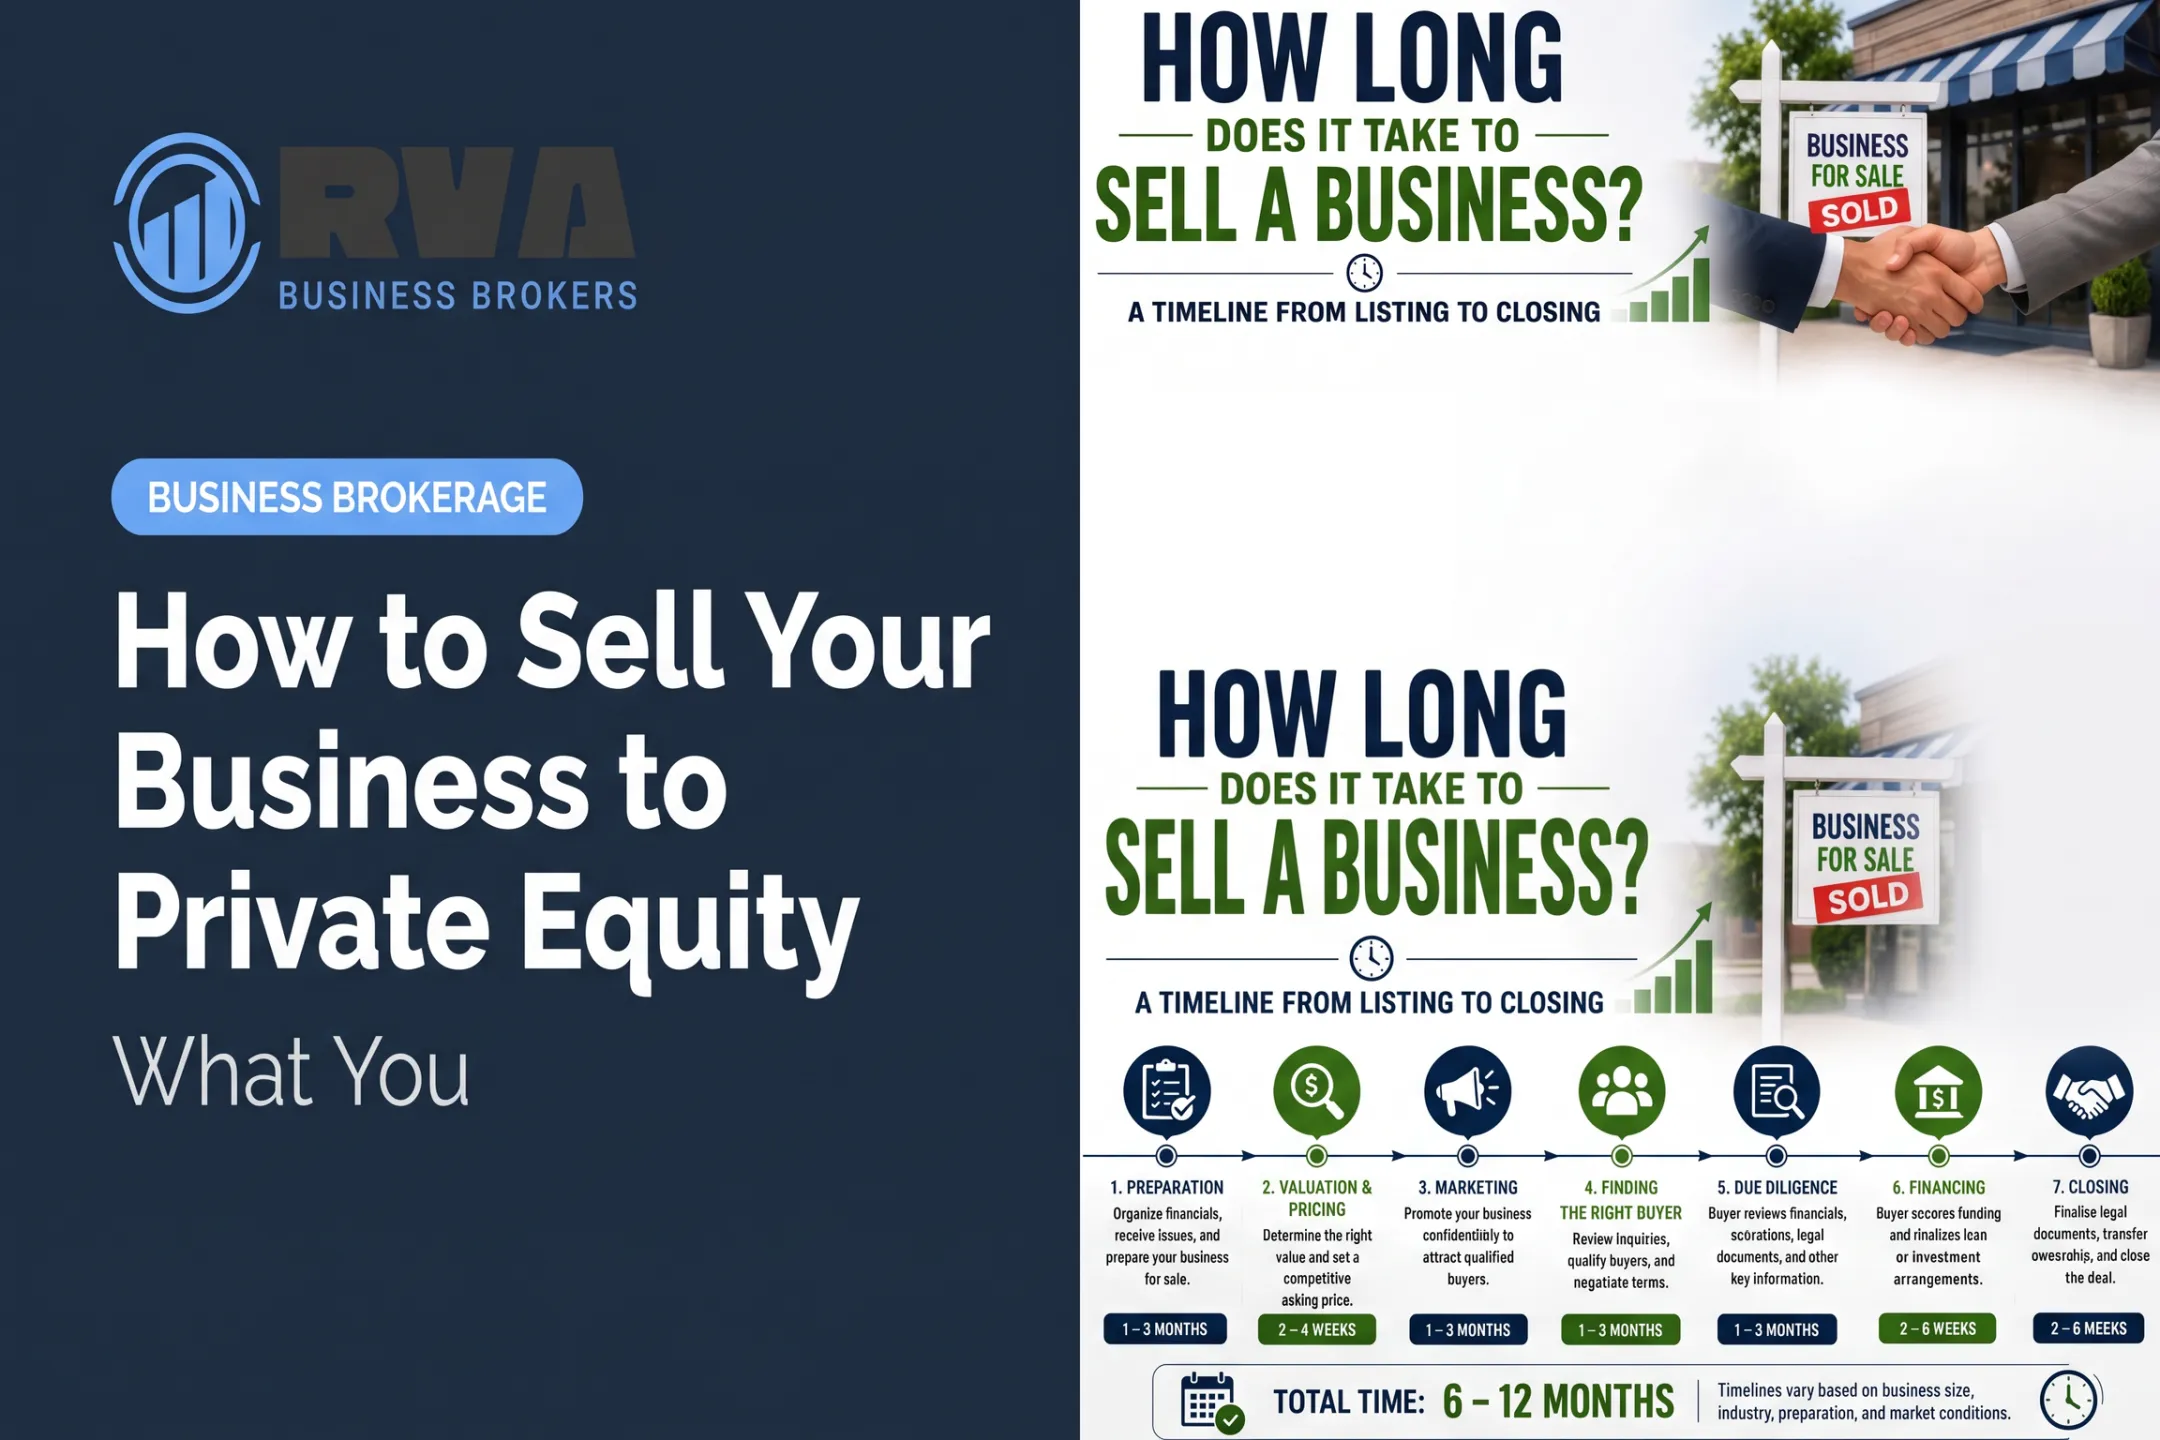
An exit-readiness roadmap is a flexible framework, not a rigid deadline. The timeline should be adjusted based on the company’s complexity, sector, and investment thesis. A 2026 EY survey of PE executives found that those who started exit preparation 12-24 months in advance reported the strongest valuation improvements.
Here’s a phased approach to building your roadmap.
Earliest Stage (24-36+ Months Out)
- Define the Exit Thesis: Identify the likely buyer universe and what a successful transaction looks like.
- Establish a Valuation Range: Get a realistic, data-driven view of the company's current worth.
- Identify the Value Gap: Pinpoint the difference between current performance and the sponsor's exit objectives.
- Assign Accountability: Clarify roles for the sponsor, board, management, and external advisors.
Value Creation Phase (12-24 Months Out)
- Prioritize Initiatives: Focus on projects with the greatest impact on sustainable earnings and risk reduction (for example, improving recurring revenue and documenting procedures).
- Track Progress: Monitor baseline metrics, monthly progress against KPIs, and the realized financial impact of each initiative.
- Address Risks: Proactively manage execution risks and document any resolved legal or financial issues.
Preparation Phase (6-12 Months Out)
- Finalize Financials: Complete financial normalization, validate forecasts, and conduct a preliminary sell-side QoE process.
- Analyze the Market: Refresh customer and market analysis to support the growth story.
- Shore Up the Team: Finalize management succession plans and prepare the team for diligence.
- Conduct Reviews: Complete legal, tax, and compliance reviews.
Go-to-Market Phase (0-6 Months Out)
- Finalize the Story: Perfect the equity story, management presentation, and buyer materials.
- Launch the Data Room: Open the fully populated and organized data room.
- Coordinate the Process: Finalize advisor roles, the buyer list, and the communications plan to maintain confidentiality and control.

Even with a clear roadmap, lower-middle-market exits still demand tight coordination across finance, operations, and the deal team. Outside advisors keep that work on schedule and buyer-ready.
Mid Atlantic Business Brokers provides confidential business valuations and sell-side transaction guidance for owners and sponsors preparing to exit. With over 40 years of experience and analysis aligned with USPAP and NACVA standards, the firm helps clients see what the business is worth today and which steps matter most before buyer discussions begin.
Use a readiness scorecard to track progress across these areas:
- Financial Quality: Are your reports clean and defensible?
- Value Creation Evidence: Can you prove the impact of your initiatives?
- Management Depth: Is the team ready to lead post-transaction?
- Operational Independence: Can the business run without you?
- Customer & Revenue Risk: Have you diversified your customer base?
- Legal & Compliance: Are there any hidden liabilities?
- Buyer Materials: Is your story compelling and your data room complete?
- Advisor Coordination: Is your team aligned and ready to execute?
Frequently Asked Questions
What does "Exit Readiness" mean?
Exit readiness is the financial, operational, commercial, and leadership work that prepares a portfolio company for sale. Done well, the business can withstand buyer scrutiny and support a higher-value exit.
What is an example of an exit strategy?
A common example is a strategic sale to a corporate buyer that wants the company’s products, customers, or market position. Sponsors may also use a secondary sale, recapitalization, or GP-led continuation vehicle, depending on goals and timing.
What is a typical PE exit?
Most private equity exits are strategic sales to corporate acquirers or sponsor-to-sponsor sales. Recapitalizations and continuation funds are also used; IPOs are a less frequent path to return capital to investors.
What are the five Ds of exit planning?
The five Ds are commonly cited events that can force an unplanned business sale: death, disability, divorce, disagreement, and distress. They highlight the importance of contingency planning for ownership transfer risk.